JAWS: Auditing Predictive Uncertainty Under Covariate Shift
PDF
Link
Code
@inproceedings{prinster2022jaws,
  title = {JAWS: Auditing Predictive Uncertainty Under Covariate Shift},
  author = {Prinster, Drew and Liu, Anqi and Saria, Suchi},
  booktitle = {Advances in Neural Information Processing Systems},
  volume = {35},
  publisher = {Curran Associates, Inc.},
  year = {2022},
  url = {https://papers.nips.cc/paper_files/paper/2022/hash/e944bacecce6b06374ac39b260348db0-Abstract-Conference.html}
}
Informal Summary
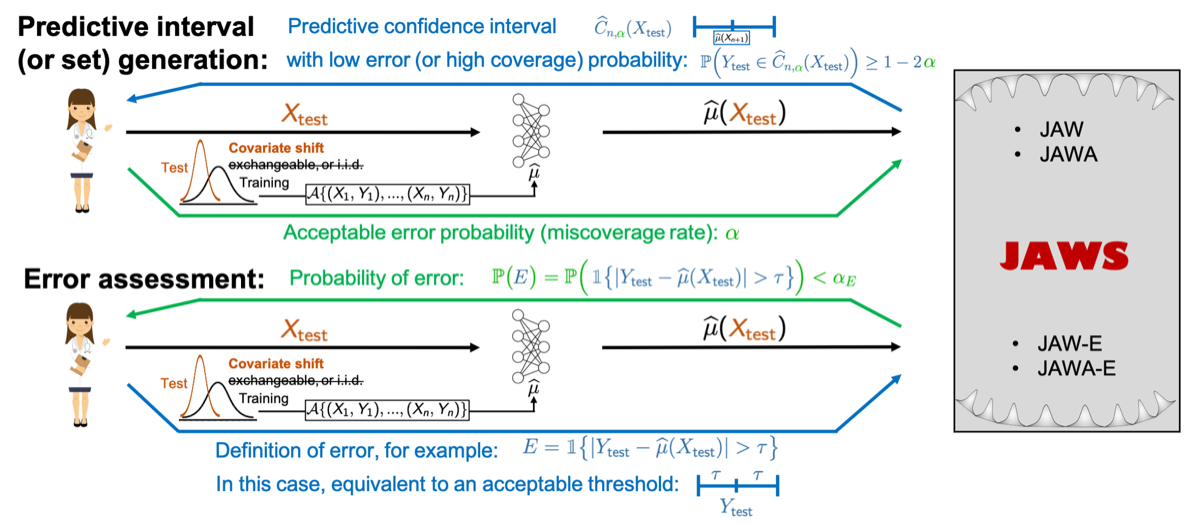
JAWS is a collection of wrapper methods for distribution-free predictive inference when the common data exchangeability (e.g., i.i.d.) assumption is violated due to shifts in the input data distribution (standard covariate shifts). JAWS is based on our core method JAW–the JAckknife+ Weighted for standard covariate shift–and also includes computationally efficient Approximations of JAW (JAWA) using higher-order influence functions.